Anthropic set the terms for its IPO on Tuesday. It plans to sell 825 million Class A shares at $70 to $78 each, price the deal on November 18 and start trading on Nasdaq under ANT on November 19. At the top of the range the company would be worth about $1.404 trillion on a fully diluted basis. Bloomberg reported a day later that the deal has already drawn orders for multiple times the shares on offer.
I read the financials in the amended S-1 and I think this is one of the best businesses to come public in a long time. I still don't plan to buy it on the first day. If the stock is higher by the time I buy, I'm willing to pay more in exchange for a few quarters of public results.
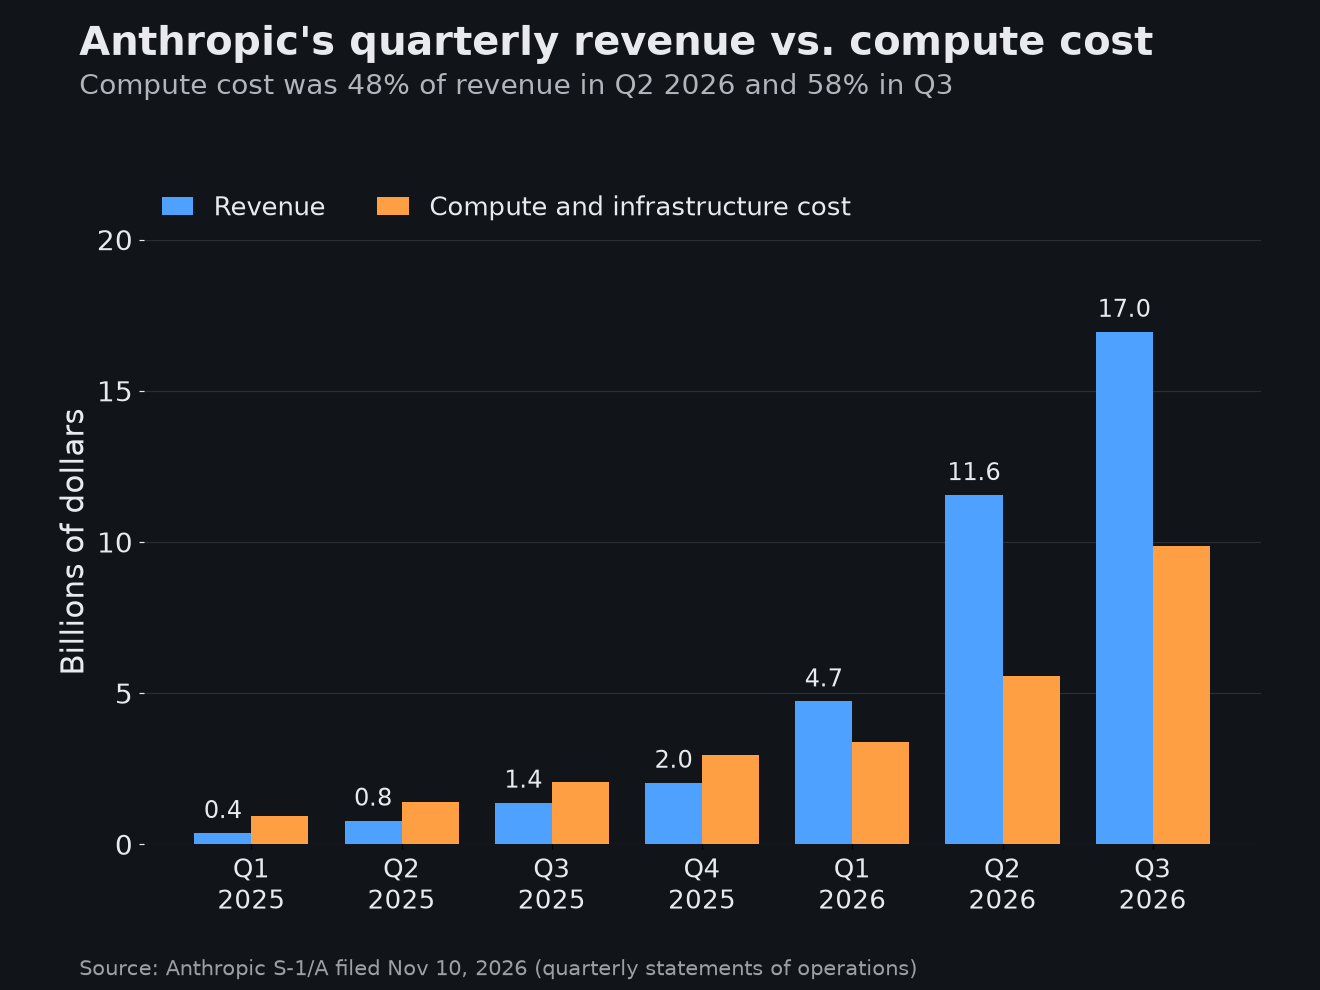
The growth is real
Revenue was $376 million in the first quarter of 2025 and $16.96 billion in the third quarter of 2026. The company also says its run-rate revenue was about $81 billion as of October 31, up $10 billion from the end of September. Customers that generated $100,000 or more over a trailing year went from more than 950 in September 2025 to more than 11,900 in September 2026. I can't think of a software company that has grown this fast at this size.
The filing is also honest about where the growth is heading. Third-quarter revenue rose 47% from the second quarter. That is still a very high number, but the second quarter rose 144% from the first. Anthropic says plainly that its run-rate growth rate "is expected to decline over time."
What gives me pause
My first concern is cost. Compute and infrastructure cost was 48% of revenue in the second quarter and 58% in the third. The company swung from $974 million of operating income to a $567 million operating loss, mostly because of $5.0 billion of compute bought under short-term commitments that it says costs "significantly more" than its multi-year contracts. I understand why they did it, since demand is outrunning capacity. It does show that margins will move around a lot from quarter to quarter.
I'm also uneasy about the price. At $1.404 trillion the stock would trade at about 17 times the $81 billion run rate. If I use third-quarter revenue times four, it's closer to 21 times. That can work if growth holds, but there is little room for a soft quarter.
Share supply is another issue. The filing says 3.6 billion shares under the 180-day lock-up can become eligible for sale before that period ends. Up to 10% of the locked shares held by non-founder directors, officers, employees and former employees can be sold starting on the first trading day. That is a lot of potential stock compared with 825 million shares in the offering.
Class A buyers also won't have much say. A single Class F share held by the seven co-founders carries 50.1% of the voting power. I'm fine with founder control at a company like this, but I would want a lower price for accepting it.
| Item | Figure |
|---|---|
| Price range | $70 to $78 |
| Class A shares offered | 825 million |
| Fully diluted value at $78 | $1.404 trillion |
| Last private round (May) | $965 billion |
| Q3 2026 revenue | $16.96 billion |
| Run-rate revenue (Oct 31) | About $81 billion |
| Q3 2026 operating income | Loss of $567 million |
What I expect
Anthropic is targeting about 20% of the deal for retail investors, against a typical 5% to 10%, according to CNBC. Vanda Research thinks it could draw record retail buying. With that much demand I expect the deal to price at or above the top of the range and open well above it. Morningstar's analyst called the company undervalued and he may be right over five years. My concern is the opening price. I think the large retail allocation will push it above what the business is worth today. The early lock-up releases could then weigh on the stock in the months after.
I plan to watch the first earnings report as a public company and look at whether compute cost falls back toward half of revenue. I also plan to watch how the stock trades as the early lock-up releases start. I think there's a good chance I get to buy it below its first-day close sometime in the first half of 2027. If I'm wrong, I'll have missed some gains in a company I like and I can accept that.