Disclosure: I have a position in AppLovin. I'm short one put and one put credit spread position on APP in Robinhood and I'm also short five puts in my Fidelity account. All of them gain when the stock goes up or holds steady. Keep that in mind as you read this.
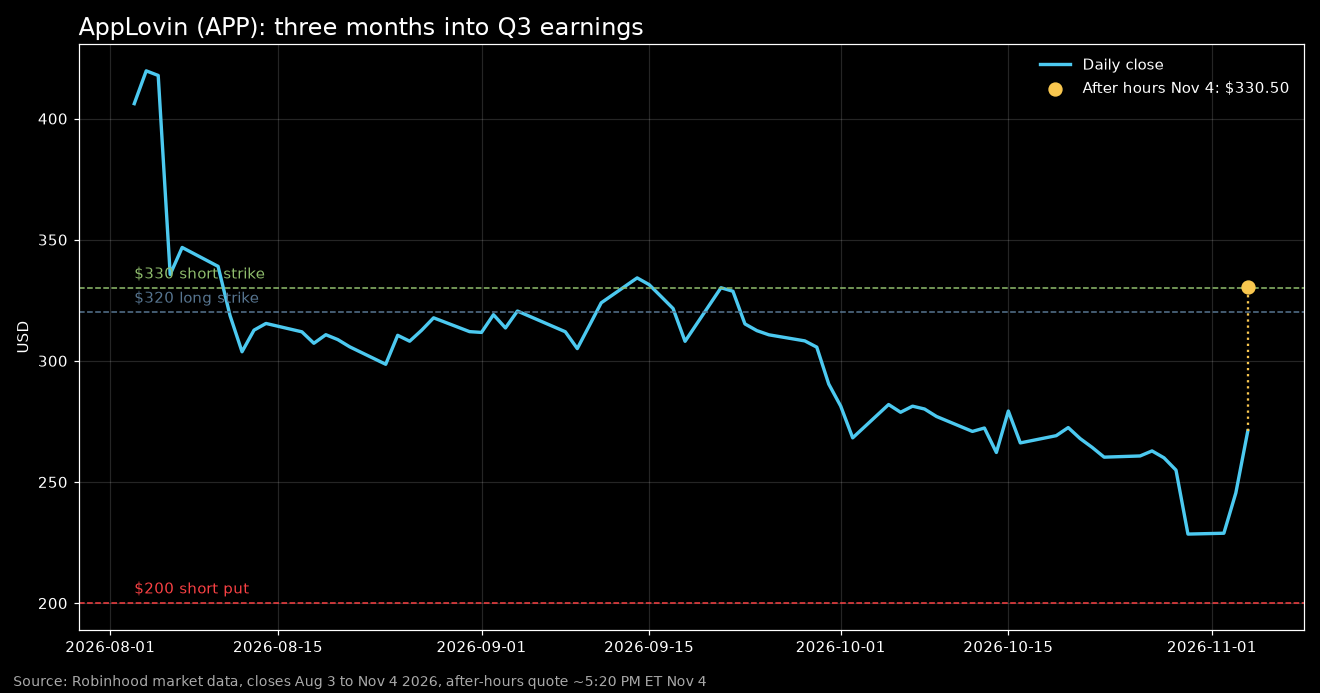
AppLovin reported its third quarter after the close today and the stock jumped about 22% in after-hours trading. It closed the regular session at $271.11 and was trading around $330 a little after 5 PM ET. Since I was on the side of the trade that wanted a calm or higher stock, this was a good evening for me. I want to write down why I made the trade, what I think the quarter says and what could still go wrong.
The numbers
Revenue was $2.185 billion, up 55% from a year ago. Analysts expected about $2.08 billion according to Investing.com. Diluted EPS was $4.30 against a consensus of roughly $4.03 to $4.04. Net income was $1.44 billion, which is a 66% net margin, and adjusted EBITDA margin was 84%. The company also produced $1.4 billion of free cash flow and spent $1.4 billion buying back shares. The board added $3.2 billion to the buyback, so $3.6 billion is now authorized (AppLovin press release).
The guidance matters more to me than the beat. AppLovin expects fourth quarter revenue of $2.365 billion to $2.395 billion. The Street was at about $2.25 billion, so the midpoint is roughly 6% higher than what analysts were modeling.
| Metric | Reported | Consensus |
|---|---|---|
| Q3 revenue | $2.185B | ~$2.08B |
| Q3 diluted EPS | $4.30 | ~$4.04 |
| Q3 adjusted EBITDA margin | 84% | ~83% (company guide) |
| Q4 revenue guide | $2.365B to $2.395B | ~$2.25B |
Why I sold puts here
Going into the print the stock was down about 65% for the year and was one of the worst performers in the S&P 500 (Barchart). Analysts had been cutting estimates and price targets for weeks after the small revenue miss in the second quarter. At the same time the business was still growing revenue around 50% a year with margins most software companies never reach. Barchart put the forward P/E at about 12. To me that looked like a stock priced for a bad quarter at a company that had not really had one.
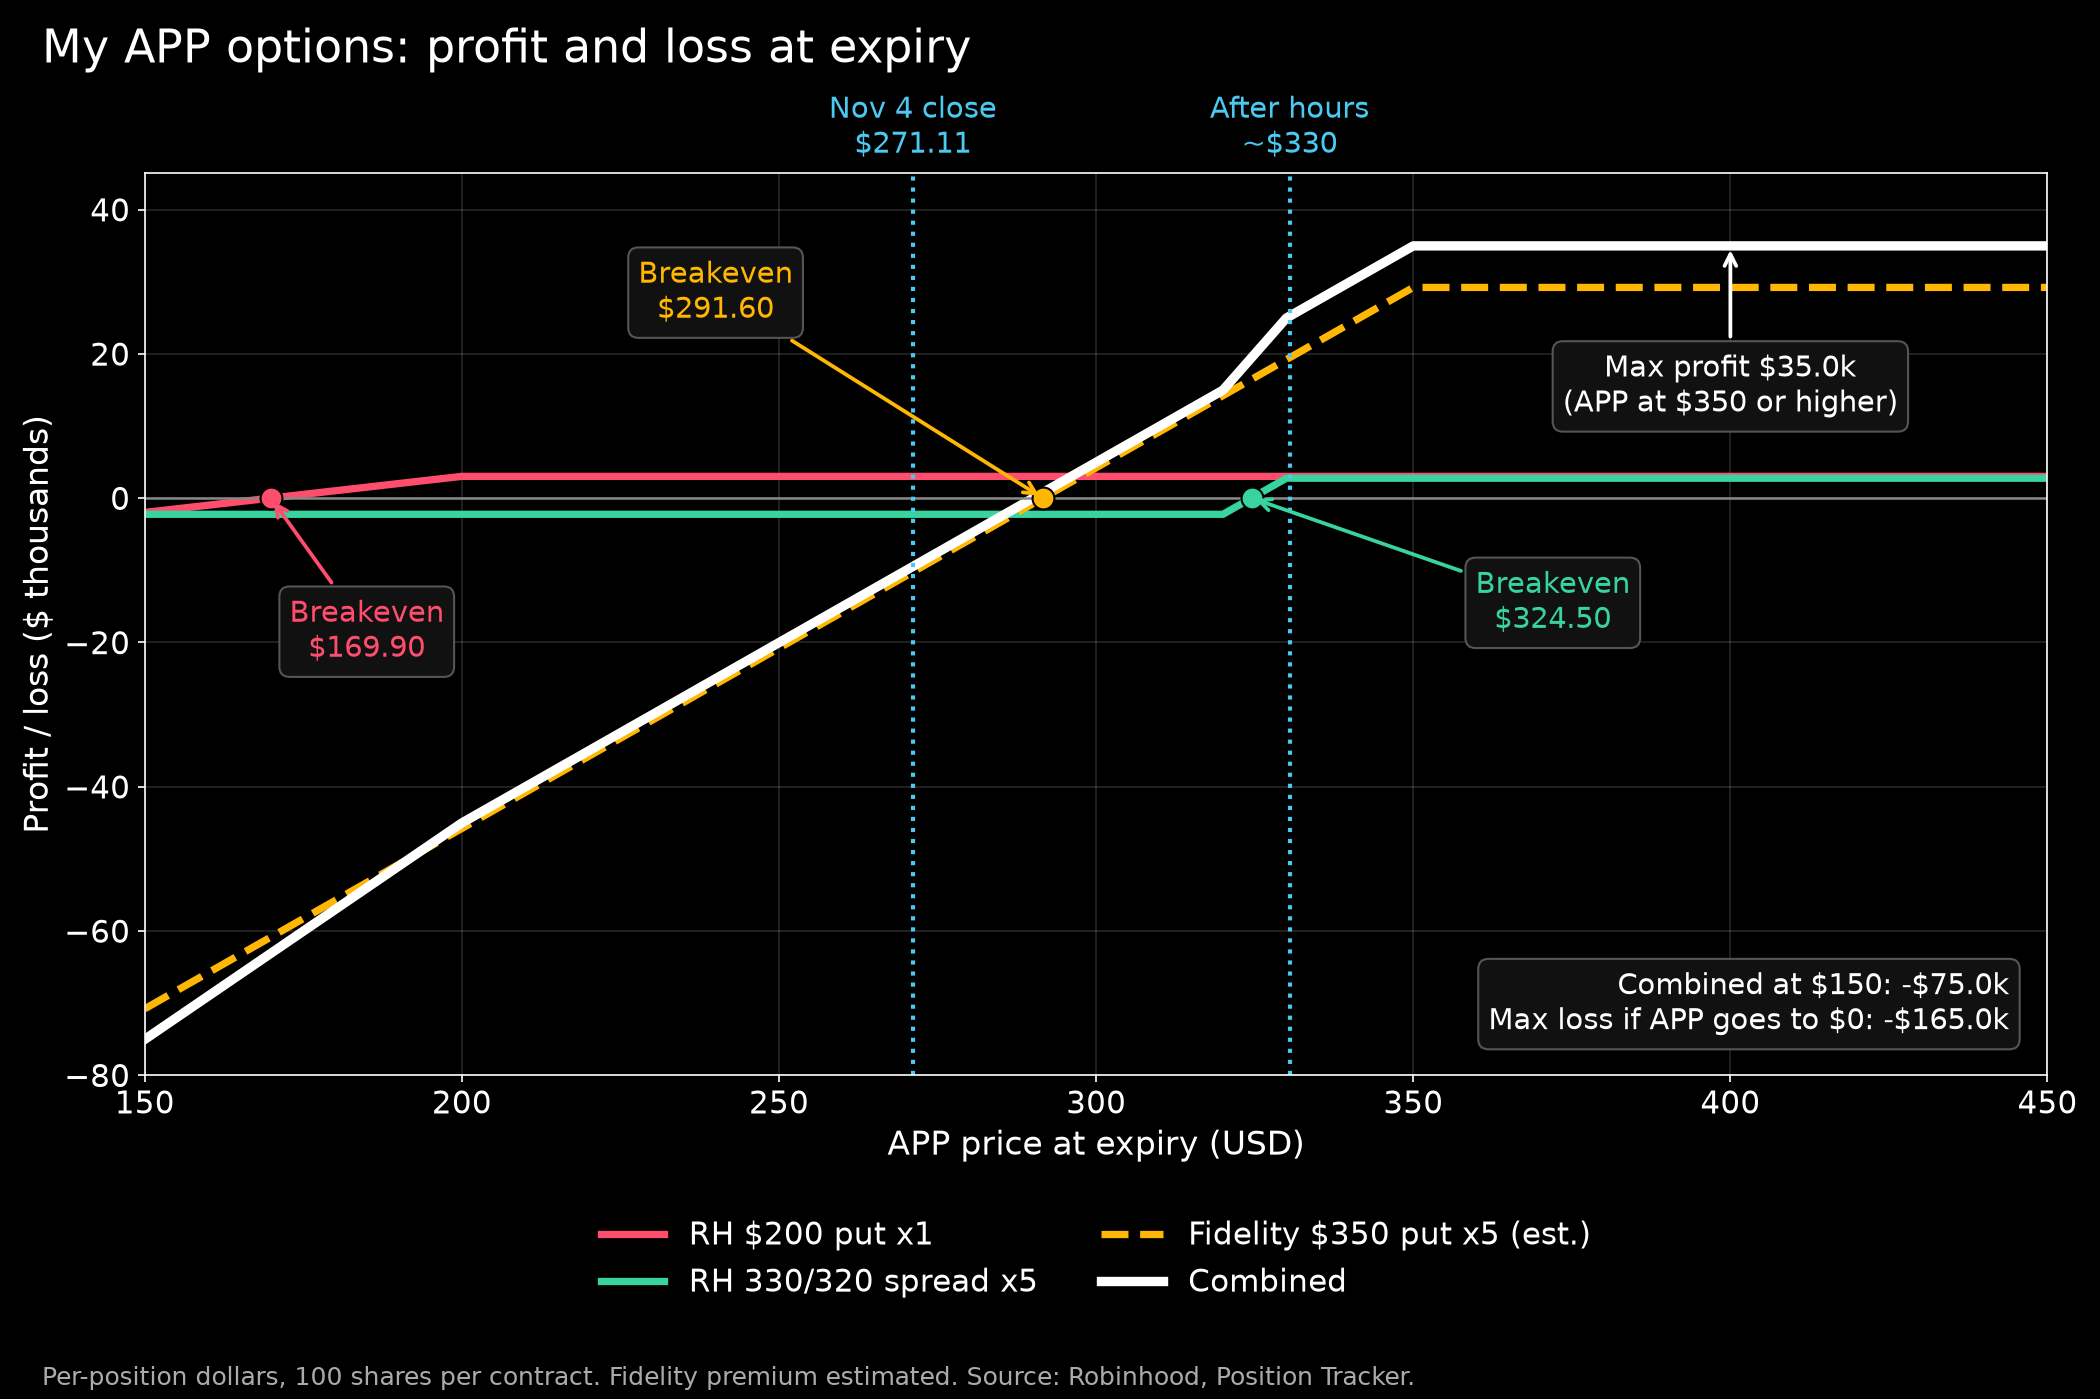
Options were also expensive because everyone expected a big move. When implied volatility is that high, selling puts means you get paid well to agree to buy a stock you already like at a lower price. On November 2 I sold a May 2027 $200 put for about $30 a share. That is a breakeven around $170, which is about 30% below where the stock was trading before the report. I was comfortable owning APP at that level.
The spread is a different story and I should be honest about it. In September, with the stock around $331, I opened one $330/$320 put credit spread position for June 2027 with five contracts. I took in $5.50 a share and the most I can lose is $4.50 a share on each contract. The stock kept falling after that, so going into today the spread was showing a loss. With the stock back near $330 after hours it is roughly where I started, so it isn't a win yet.
In Fidelity I sold five January 2027 $350 puts. I don't have the exact fill in front of me, so the premium below is an estimate of about $58.40 a share. That puts the breakeven around $291.60.
| Position | Strikes | Expiry | Premium collected | Max profit | Max loss | Breakeven | Mark at Nov 4 close |
|---|---|---|---|---|---|---|---|
| Robinhood short put x1 | $200 | May 21, 2027 | $30.10 | $3,010 | $16,990 | $169.90 | $19.20 |
| Robinhood put credit spread x5 | $330 / $320 | Jun 17, 2027 | $5.50 | $2,750 | $2,250 | $324.50 | $9.20 |
| Fidelity short put x5 | $350 | Jan 15, 2027 | ~$58.40 (est.) | ~$29,200 | ~$145,800 | ~$291.60 | $96.40 (midday) |
Premiums and marks are per share and each contract covers 100 shares. Max loss for the short puts assumes the stock goes to zero after I'm assigned. Options don't trade after hours, so these marks are from the regular session and will reset when the market opens Thursday.
The risk next to the reward
The Fidelity puts carry most of the risk. They have the highest strike and the most premium, but they only break even if APP is above about $292 in January. At the close today the stock was below that, so the after-hours move is what pulled that position back toward profit. The spread needs APP above $330 by June to keep the full credit and its breakeven is $324.50. Its loss is capped at $2,250, which makes it the smallest risk of the three. The $200 put is the safest position since the stock would have to fall about 40% from the after-hours price before it loses money.
What the quarter says about the ad business
The concern going in was that the Axon ad engine had peaked and that gaming advertisers were spending less. UBS cut its target from $790 to $414 citing slower consumer growth and tougher competition in gaming. A 55% growth rate and a guide well above consensus do not fit that concern. Management had said in August that model upgrades were deployed right after the second quarter ended and this quarter is the first evidence that those upgrades worked.
The margin is the part I find most convincing. An 84% adjusted EBITDA margin while spending more on compute means the extra revenue is falling almost straight through to profit. That is why the company can buy back $1.4 billion of stock in a single quarter and still raise the authorization.
What would make me wrong
This is still one company and the stock has shown it can lose 15% to 20% on a small miss, as it did in August. A lot of my upside is tied to one name, which is a concentration risk I accept but don't ignore. The growth also depends on AI model improvements arriving on schedule. If the next upgrade disappoints or the push into non-gaming advertisers stalls, the multiple could compress again. A big after-hours pop can also fade by the next close.
My plan is to keep the $200 put open, since it would take a collapse for it to be a problem. I will watch the spread and the Fidelity puts more closely because their breakevens are much closer to the current price. My expectation is that the estimate cuts reverse over the next few weeks and the stock holds most of this move into year end. If it gets back toward $400 I would consider closing everything early and taking the profit.